On SpaceX's Q3 2026 earnings call, Elon Musk said he would be surprised if the company brought on less than 13 GW of AI compute by the end of 2027. SpaceX's own report shows 1.7 GW of nameplate compute at September 30, up 0.3 GW in the quarter. The quarter before added 0.4 GW.
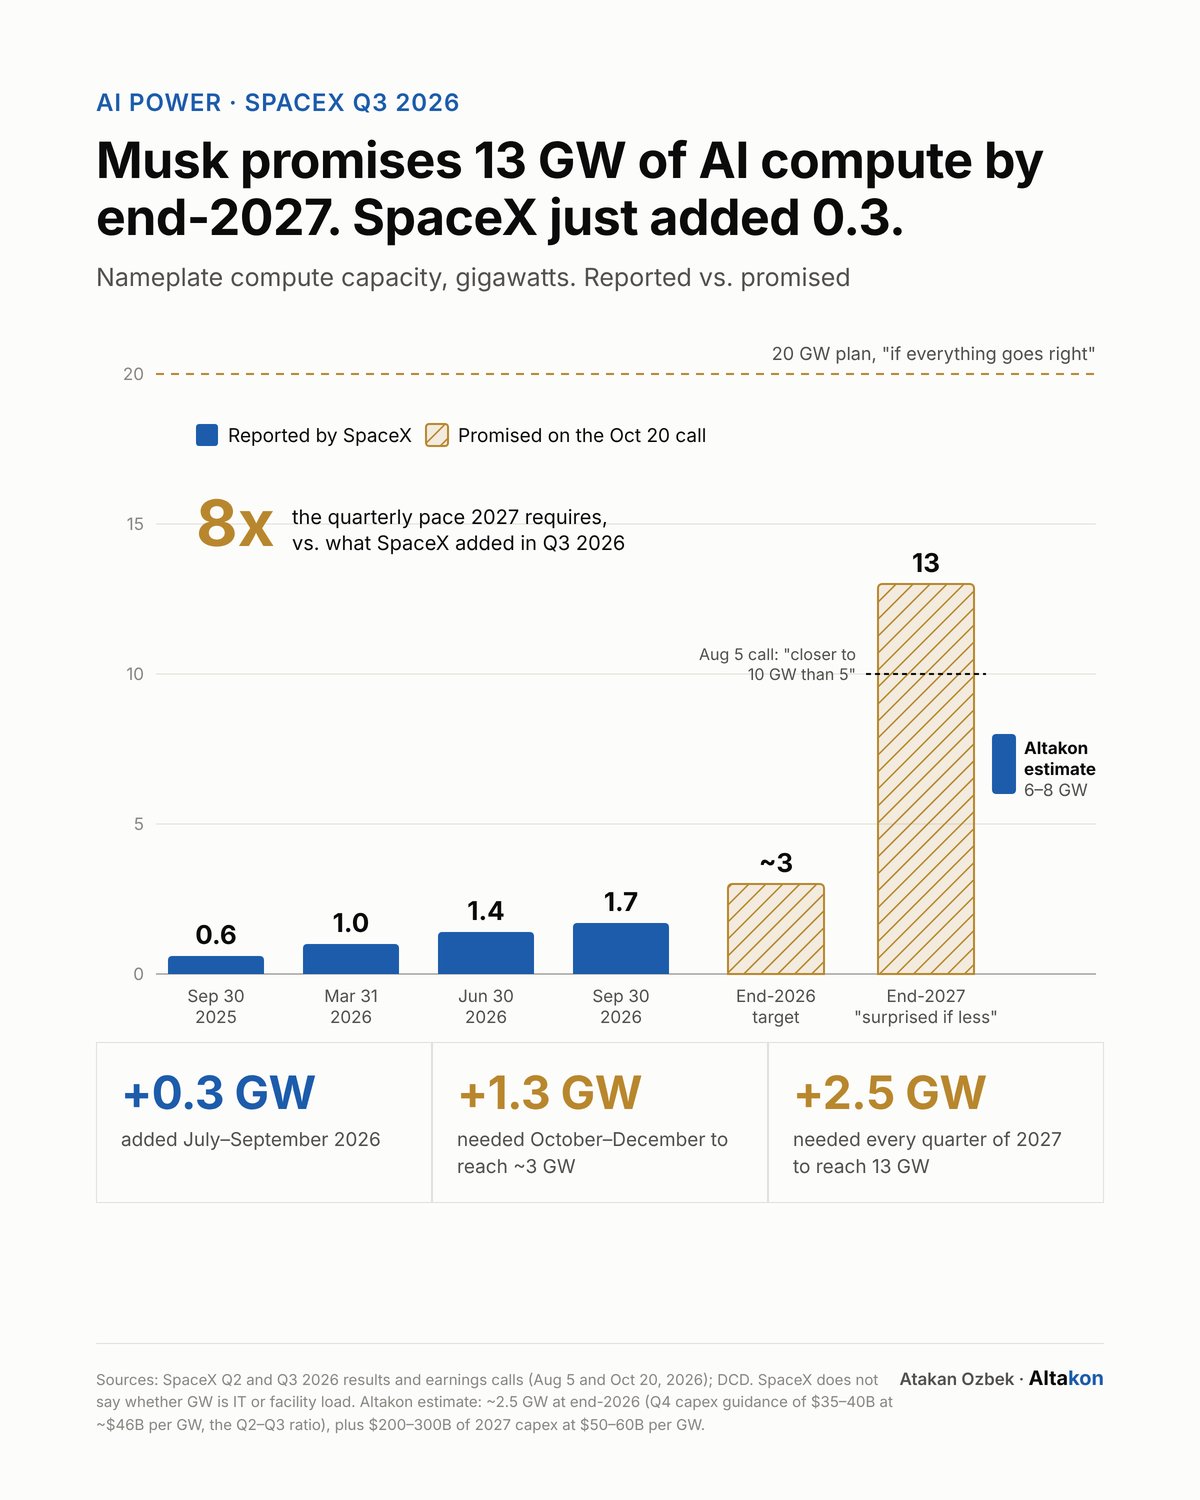
Reaching 13 GW means adding about 2.5 GW every quarter of 2027, eight times the pace just reported. Even the end-2026 target of about 3 GW implies 1.3 GW in a single quarter. And the goal has moved: on the August 5 call, the end-2027 guide was “closer to 10 GW than 5.” Two months later it is 13.
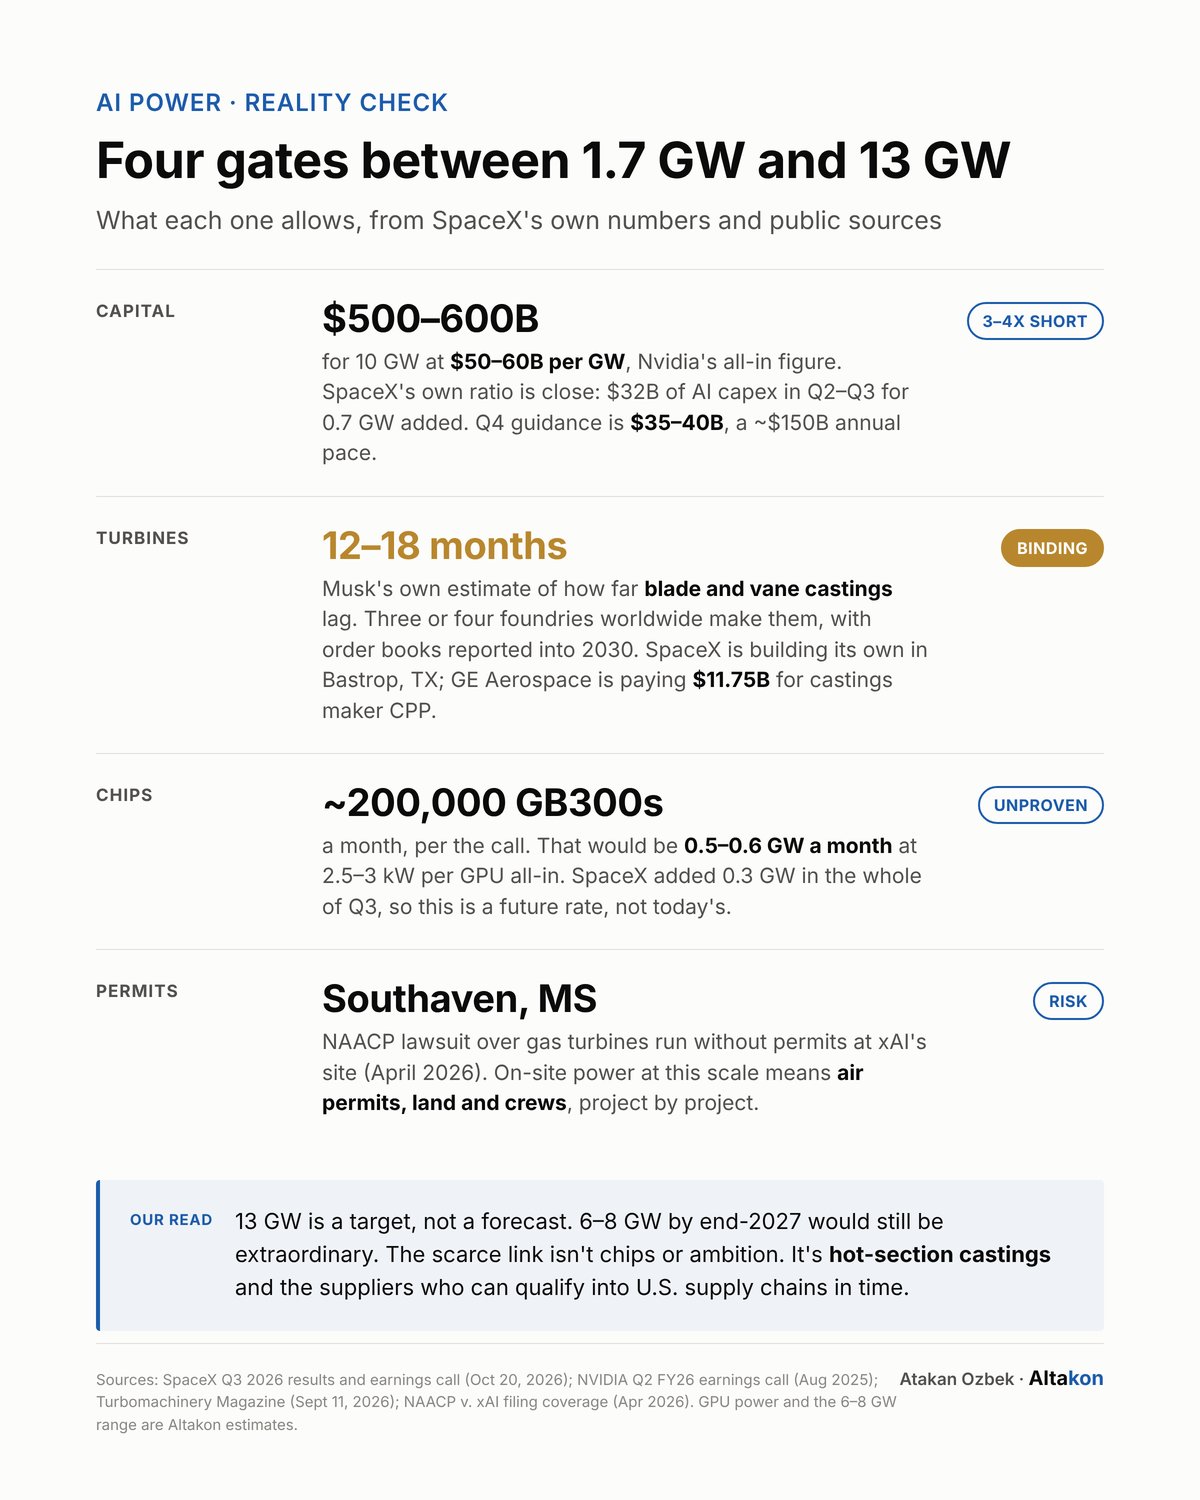
Capital. Nvidia puts a gigawatt of AI capacity at $50–60B all-in. SpaceX's own spending lands close: about $32B of AI capex in Q2 and Q3 for 0.7 GW added. Ten more gigawatts is $500–600B, against Q4 capex guidance of $35–40B, a ~$150B annual pace. Leasing can bridge part of the gap, at a price: CoreWeave's bonds have traded at yields around 15–16%.
Chips. Musk spoke of roughly 200,000 GB300s a month. At 2.5–3 kW per GPU all-in, that would be half a gigawatt a month. SpaceX added 0.3 GW in the whole of Q3, so this is a future rate, not today's.
Permits. On-site power at this scale needs air permits, land and crews, project by project. xAI's Southaven, Mississippi site already faces a lawsuit over gas turbines run without permits.
Turbines. In Musk's own words, casting turbine blades and vanes is “a really difficult bottleneck,” 12 to 18 months behind. Three or four foundries worldwide make them, with order books reported into 2030. SpaceX is building its own foundry in Bastrop, Texas, and GE Aerospace is paying $11.75B for castings maker CPP. When a rocket company and a jet engine maker both buy their way into the same bottleneck, it is real.
Our read: 13 GW is a target, not a forecast. Our estimate is 6–8 GW by end-2027, based on Q4 spending reaching about 2.5 GW by year-end plus $200–300B of 2027 capex at $50–60B per GW. That would still be an extraordinary build. SpaceX does not say whether its gigawatts are IT load or facility load; facility load runs roughly 20% higher.
The opening is in the scarce links: hot-section castings and forgings, and the engines, turbines and packaged power that don't wait on them. Manufacturers outside the U.S. with qualified capacity in these parts have a window U.S. buyers will pay for, if they can qualify into U.S. supply chains in time. If you make castings, forgings or packaged power and the U.S. is in your 2027 plan, Altakon would welcome the conversation.
Sources
- SpaceX Q3 2026 results and earnings call, October 20, 2026.
- SpaceX Q2 2026 earnings call, August 5, 2026 (DCD coverage).
- NVIDIA management estimate of $50–60B per GW of AI infrastructure.
- Turbomachinery Magazine, September 11, 2026 (castings bottleneck, SpaceX foundry, GE Aerospace–CPP).
- SemiAnalysis 2027 data center capacity forecast (~50 GW).
- NAACP lawsuit coverage, April 2026 (Southaven, MS).
- Altakon estimates: GPU power, 6–8 GW range.